EasyPost Goes Public at $479M Valuation Through ADAC SPAC Merger
Seeking Alpha · November 18, 2026
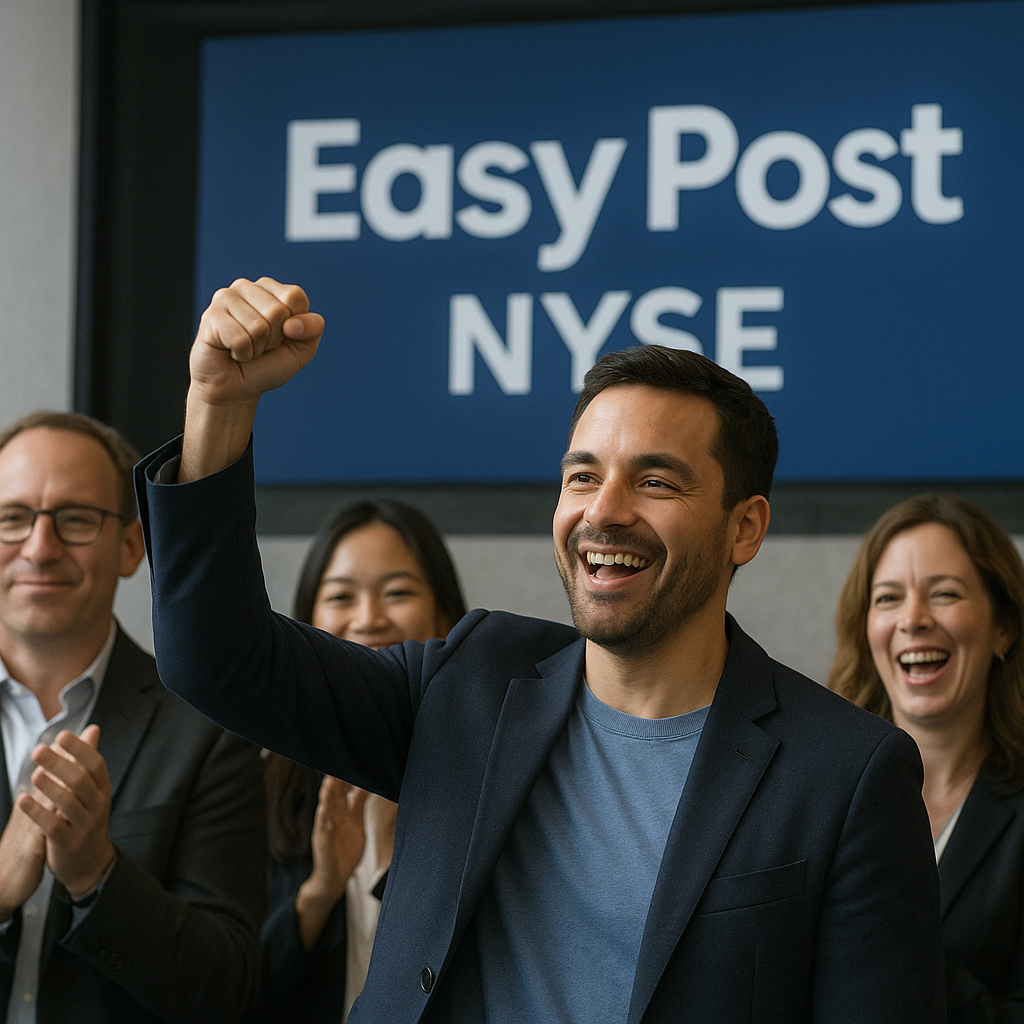
Key takeaways
- EasyPost, a shipping and logistics API provider, is going public via a SPAC merger with ADAC at a $479 million valuation.
- The deal offers a faster, negotiated path to public markets compared to a traditional IPO.
- Post-merger performance will hinge on EasyPost's ability to retain e-commerce clients and manage carrier pricing pressures.
What's Happening
EasyPost, the shipping and logistics API company, is heading to the public markets through a merger with ADAC, a special purpose acquisition company (SPAC). The deal values EasyPost at roughly $479 million — a number that will shape how investors view the company's growth story once shares start trading.
For those unfamiliar, EasyPost built its business helping e-commerce platforms, marketplaces, and logistics companies manage shipping logistics through a single API — rate shopping across carriers, label generation, tracking, and address verification. It's the kind of infrastructure play that powers a lot of the shipping experience you never actually see as a shopper, but that online sellers rely on daily.
Why a SPAC, Why Now
SPAC mergers have had a rocky reputation since the 2021 boom-and-bust cycle, but they've continued to serve as an alternative path to public markets for companies that want to skip the traditional IPO roadshow. For a company like EasyPost, merging with an already-public shell company like ADAC offers a faster route to trading status, built-in capital from the SPAC's trust account, and a negotiated valuation rather than one set by IPO-day market demand.
A $479 million valuation puts EasyPost in the mid-size range for recent SPAC deals — not a mega-cap unicorn story, but a meaningful marker for a company that's spent years building out shipping infrastructure for a rapidly growing e-commerce economy.
What Investors Will Be Watching
Once the deal closes, expect scrutiny on a few fronts: revenue growth, customer retention among e-commerce and logistics clients, and how EasyPost's take rate holds up as shipping carriers adjust pricing. SPAC-merged companies also tend to face early volatility as early investors and SPAC sponsors look to cash out, so trading patterns in the first few months post-merger are often choppy regardless of underlying business performance.
For the broader logistics-tech space, this deal is also a signal. If EasyPost trades well post-merger, it could open the door for other shipping and fulfillment infrastructure companies eyeing public listings. If it struggles, expect continued caution around SPAC-driven logistics plays.
The Bottom Line
This is a notable step for a company that's quietly become part of the plumbing of online shopping. Whether a $479 million valuation holds up will depend less on the SPAC mechanics and more on whether EasyPost can keep growing its customer base in a shipping industry that's constantly being squeezed by carrier price changes and e-commerce volume swings.
Why it matters
This deal matters to anyone tracking e-commerce infrastructure and SPAC market activity, since EasyPost's public debut could signal renewed investor appetite for logistics-tech companies. It's also a useful case study in how SPAC mergers continue to serve as an alternative IPO path in 2024-2025.
Want deals on what you love?
Val finds local offers matched to your interests — free to start.
Meet Val