Peloton Earnings Beat: EPS of $0.19 Crushes Estimates, Revenue Tops $559M
Seeking Alpha · November 5, 2026
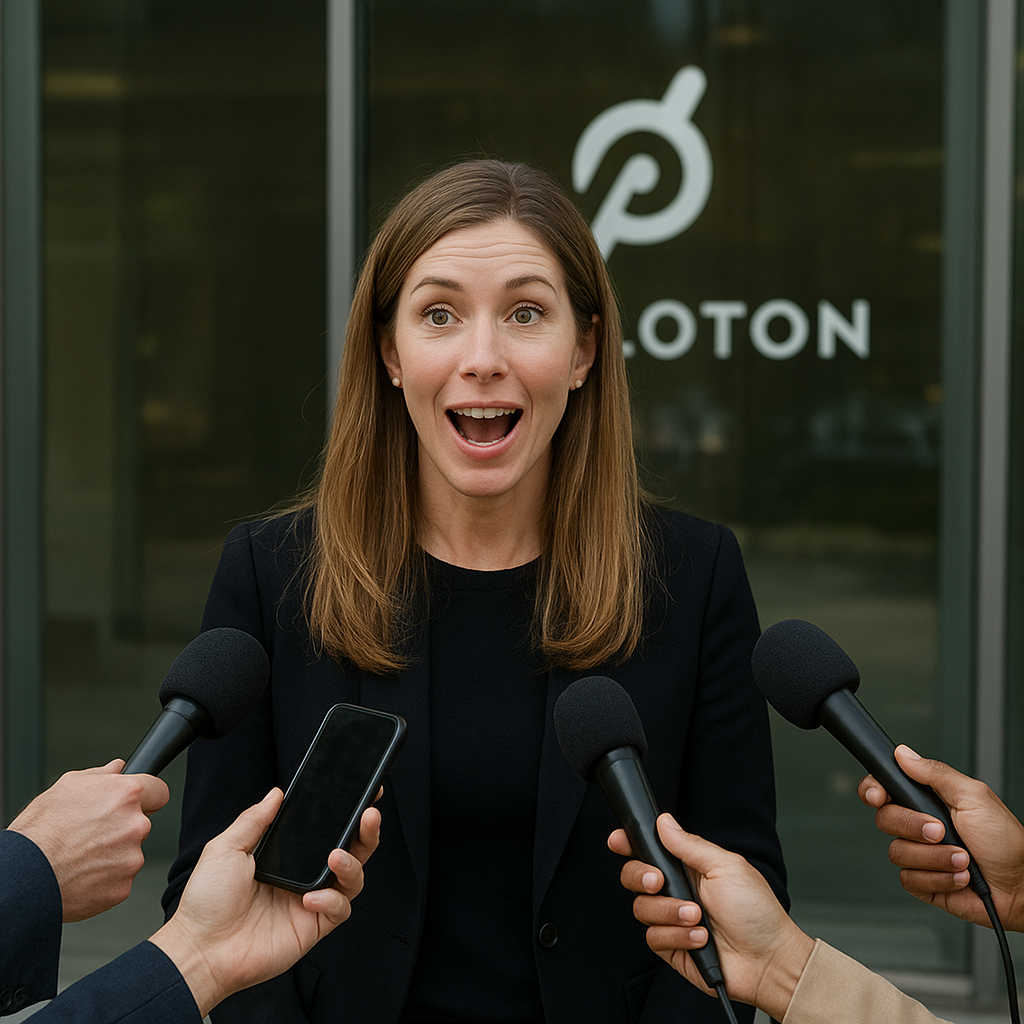
Key takeaways
- Peloton reported GAAP EPS of $0.19, beating analyst estimates by $0.08 per share.
- Revenue hit $559.2 million, topping expectations by $7.04 million, showing growth alongside profitability.
- The beat suggests Peloton's cost-cutting and subscription-focused strategy is gaining traction after years of post-pandemic struggles.
Peloton Just Beat the Street
Peloton dropped its latest earnings report and surprised a lot of people who'd written the company off. GAAP EPS came in at $0.19, beating analyst estimates by $0.08. Revenue landed at $559.2 million, topping expectations by $7.04 million. For a company that's spent the last few years associated with pandemic-era hype and post-pandemic struggles, this is a real headline.
Why This Beat Matters
Peloton's story since 2021 has been rough: plummeting demand after the at-home fitness boom faded, leadership shakeups, layoffs, and a stock price that cratered from its highs. A profitable quarter with revenue growth above projections signals the company's cost-cutting and subscription-focused pivot might actually be working. Instead of chasing hardware sales (bikes and treads), Peloton has leaned hard into its recurring subscription revenue — the higher-margin, more predictable business that investors actually want to see.
Beating on both the top line (revenue) and bottom line (earnings) in the same quarter is the kind of signal that can shift analyst sentiment. It suggests management's restructuring — trimming expenses, renegotiating costs, focusing on retention over new subscriber chasing — is translating into real financial discipline, not just a one-off.
What to Watch Next
One quarter doesn't make a turnaround story permanent. The real test for Peloton is whether this profitability is sustainable or a product of favorable cost comparisons and one-time efficiencies. Investors will be watching subscriber churn, the pace of hardware sales, and whether the company can keep growing revenue without sacrificing the margin gains that drove this EPS beat.
It's also worth watching how the market reacts in the days following the report. Earnings beats don't always translate into stock gains if guidance for future quarters disappoints or if management signals caution about demand. Peloton has surprised to the upside before and still seen shares slide on soft forward guidance, so the full picture depends on what executives say about the quarters ahead.
The Bigger Picture
Peloton has become something of a bellwether for the broader "at-home everything" trend that exploded in 2020 and 2021. Its recovery — or lack thereof — offers a window into how durable some of those pandemic-era consumer habits really were. A beat like this doesn't erase years of struggle, but it does give the bulls something concrete to point to, and it keeps Peloton's turnaround narrative alive heading into the next earnings cycle.
Why it matters
If you're tracking Peloton as an investor, subscriber, or just someone curious about the fitness industry's post-pandemic shakeout, this earnings beat is a meaningful data point in the company's turnaround story. It signals whether Peloton's cost discipline and subscription pivot can translate into sustained profitability rather than one-off gains.
Want deals on what you love?
Val finds local offers matched to your interests — free to start.
Meet Val